Your Net Worth is Not Your Retirement Income, And You Can't Wait Until 71 to Fix It.
Your balance sheet shows what you own. But it doesn't show what lands in your account each month for the next 30 years, after taxes, timing, and withdrawal order take their cut.
The free 60-second assessment shows which parts of your retirement income are covered, and which parts nobody has checked before.
60 seconds • Reviewed by a licensed advisor • Free 30-minute consultation • Nothing to buy
Most people are confident about the wrong number
- Years of accounts aren't a plan. Most people have policies and accounts collected over decades, with no single design behind them.
- Business value isn't retirement income. An exit is an event. Income is the system that runs for thirty years after it.
- Home equity isn't a paycheque. Your house is worth a lot and pays you nothing until you act.
- A pension is a foundation, not the whole house. And your statement balance isn't what you get to spend.
Six questions a retirement plan should answer
- 1Goals: What you want retirement to make possible.
- 2Income: Where it comes from, and how long it lasts.
- 3Spending: Across active, slower, and later years.
- 4Timing: When you stop working, start benefits, touch which account.
- 5Risks: What could interrupt the income.
- 6Next decisions: The two or three worth making now.
Four situations, four different conversations
The foundation is solid. The questions sit on top: CPP and OAS timing, what your personal assets are for, how much income is exposed to tax.
Your net worth has to be sold or transitioned before it becomes income. Timing, liquidity, family, and the life after ownership deserve their own conversation.
Staying, moving, downsizing and borrowing are four different retirement plans.
Or you keep saying one more year. Both are decisions. What does the extra year actually change?
Some of this runs on a schedule, whether you're ready or not
- RRSP. In the year you turn 71, your RRSP has to become income — a RRIF or an annuity. Saving stops being the question.
- CPP. CPP has a window, not an answer. Start between 60 and 70 — less for longer, or more for less time. What’s right depends on your whole income picture, not a rule of thumb.
- OAS. OAS can be deferred past 65 to increase it, and clawed back if income crosses the threshold. Both interact with your withdrawals.
- Withdrawal order. Withdrawal order is its own decision. Sequence affects how much income survives the tax return.
Source: Canada Revenue Agency and Government of Canada guidance.
The part almost nobody has reviewed
Retirement income planning assumes you're both still here and still well. Those two assumptions carry the most weight, and nobody stress-tests them.
A serious illness in your early sixties arrives when your income is least flexible. Care costs can land years early. If one of you passes away first, the household keeps most of its expenses and loses part of its income.
Protection isn't bolted onto the side of a plan. It's what keeps the income standing when life interrupts the assumptions.
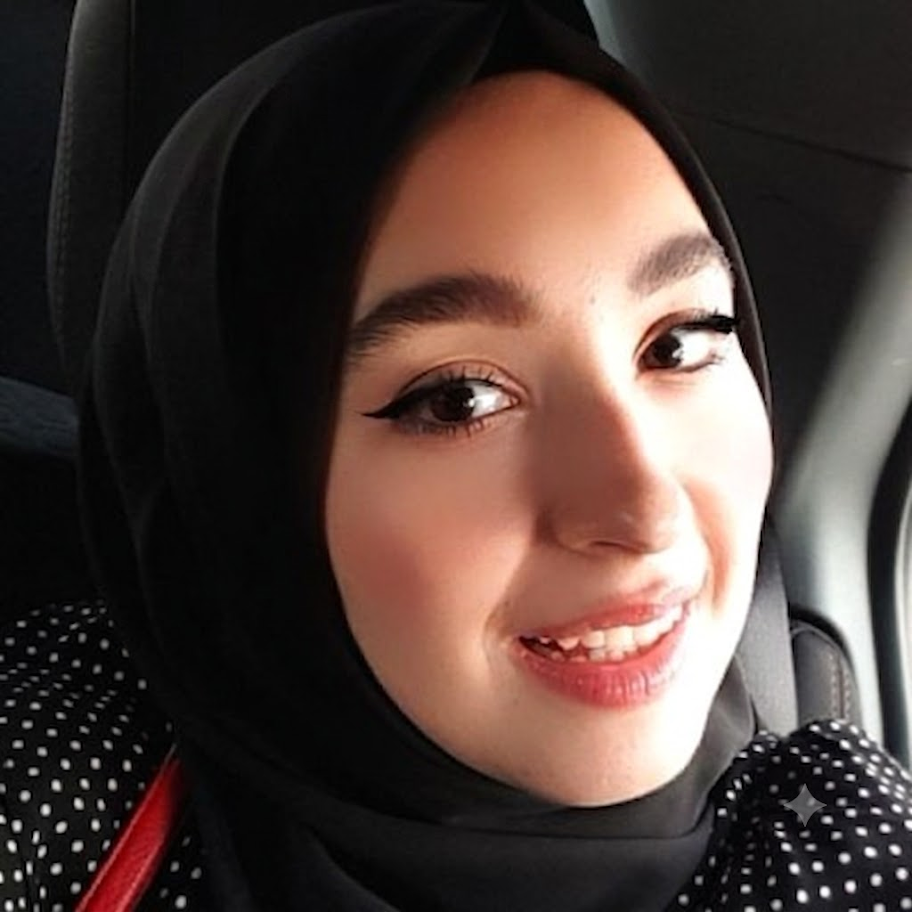
Najwa El-Farkh reads every submission herself
Najwa is the founder of ELF Advisory and a licensed life and health insurance advisor in Ontario. Her work is retirement income: turning what you've accumulated into dependable income you can count on, and protecting it.
She doesn't manage portfolios, pick investments, file taxes, or draft wills. Where that's needed, she coordinates with the people licensed to do it. What ELF Advisory does is the layer above the accounts — which is where the gaps usually are.
Sixty seconds now, a conversation when it suits you
Sixty seconds of questions. Najwa reviews your answers personally. Then a free 30-minute conversation where she walks you through what she found. If nothing needs fixing, she'll say so. She does these herself, so weekly slots are limited.
Common questions
Is this a sales call?
It's a review. Najwa is paid when someone becomes a client and will say plainly if she can help. No pressure inside the 30 minutes.
What does it cost?
The assessment and consultation are free. Paid engagements are quoted upfront.
I already have an advisor.
Keep them — most handle the accounts, but few handle the income layer above them.
Sixty seconds now, or another year of not knowing
You spent decades building this. Spend a minute finding out what it pays you.
60 seconds • Reviewed by a licensed advisor • Free 30-minute consultation • Nothing to buy